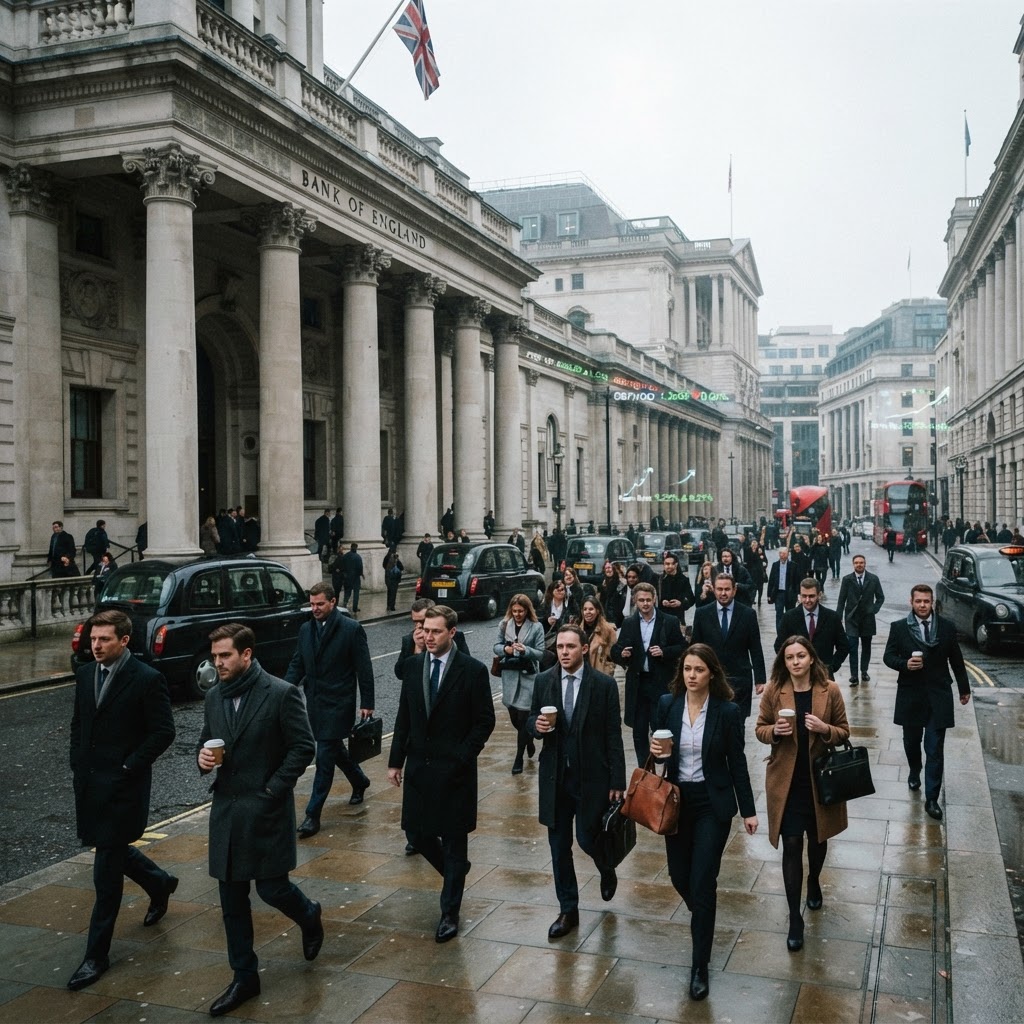
Equities Tread Water as Investors Prepare for Imminent Bank of England Tightening
The FTSE 100 has maintained a resilient stance as market participants weigh the inevitability of a rate increase. With inflation proving stubborn, the City is braced for a shift in monetary policy that could reshape the cost of borrowing for households and businesses alike.
CW
Charlotte Webb
Finance Correspondent
Published 30 October 2026·about 4 hours ago 3 min read
Text
TopicsFTSE 100Bank of EnglandUK EconomyInterest RatesInflationMonetary PolicyFinancial Markets
About the Author
CW
Charlotte Webb
Finance Correspondent
Charlotte Webb reports for National Post UK with a focus on rigorous analysis and authoritative journalism — a trusted voice across British public life.
Reader Discussion · 6
Subscribers can join the conversation.
SUBSCRIBE TO COMMENT →E
Eleanor Vance30 Oct
It is a standard reaction to a tightening cycle. The markets are simply pausing to digest the news before the next move, which is exactly what one would expect from professional investors.
M
Michael Roberts30 Oct
I find it hard to see any meaningful growth until the cost of borrowing stops climbing. I will be staying on the sidelines with my cash savings until the picture clears up.
F
Fiona Campbell30 Oct
The base rate needs to go up to tackle inflation properly, even if it hurts the equity markets in the short term. We cannot keep kicking this can down the road indefinitely.
D
David Thorne30 Oct
People keep talking about the resilience of the FTSE 100, but is it really resilience or just a lack of better places to park capital? It feels like we are walking on eggshells.
S
Sarah Jenkins30 Oct
I have shifted my portfolio into more defensive stocks recently. With the Bank of England likely to tighten further, there is just no point in chasing high-growth tech stocks right now.
A
Arthur Penhaligon30 Oct
It feels like we have been waiting for this interest rate hike for months now. The market is just pricing in the inevitable, but I worry about how much more pressure households can actually take.