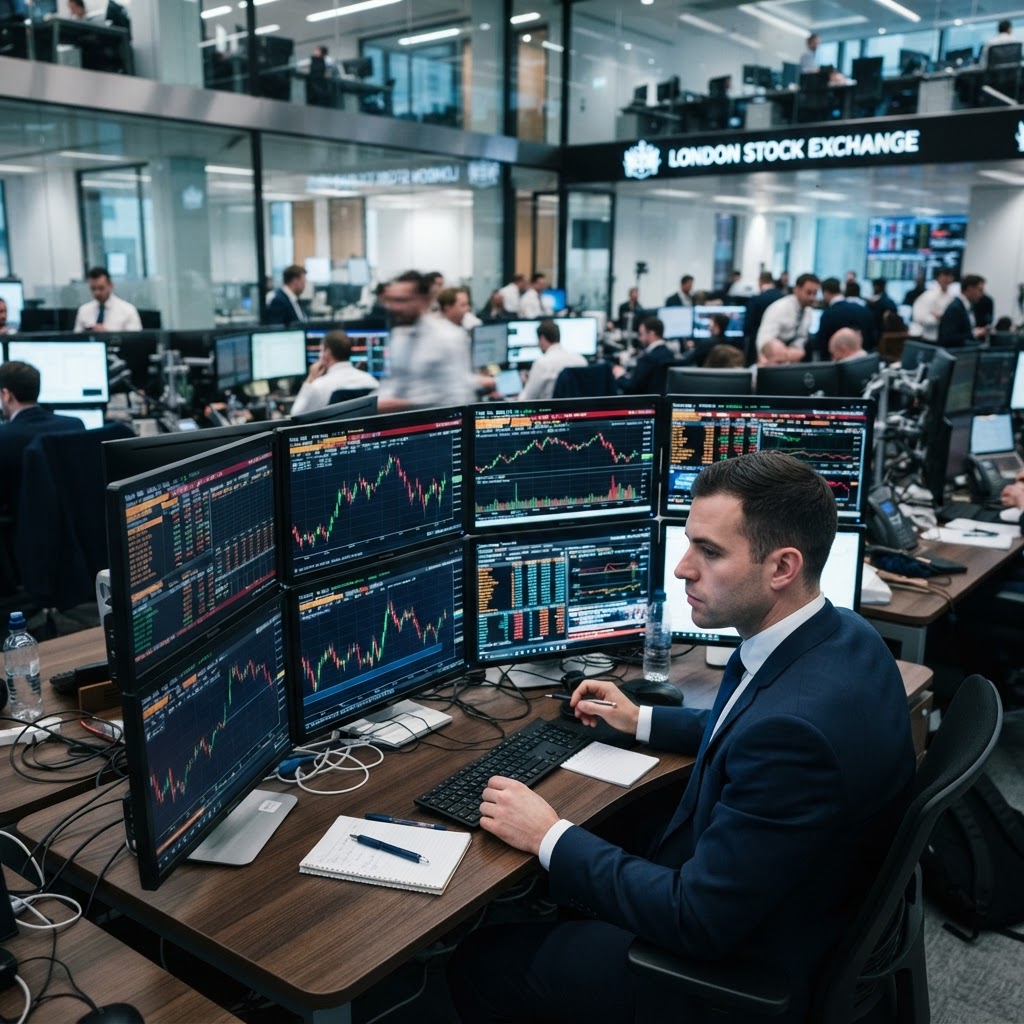
London Markets Maintain Steady Course as Inflation Data Stirs Rate Speculation
The FTSE 100 has demonstrated characteristic resilience this Tuesday, climbing 0.38 per cent to 10,731 points. Investors are currently recalibrating their portfolios as they balance persistent inflationary pressures against the cooling expectations for Bank of England intervention.
AP
Alice Pemberton
Finance Correspondent
Published 27 October 2026·about 3 hours ago 3 min read
Text
TopicsFTSE 100Bank of EnglandUK BudgetInflationCity of London
About the Author
AP
Alice Pemberton
Finance Correspondent
Alice Pemberton reports for National Post UK with a focus on rigorous analysis and authoritative journalism — a trusted voice across British public life.
Reader Discussion · 5
Subscribers can join the conversation.
SUBSCRIBE TO COMMENT →R
Robert Sterling27 Oct
Markets always react to speculation, but I would advise investors to look at the long-term fundamentals rather than chasing today's headlines. We have seen this pattern many times before.
L
Linda Mckenzie27 Oct
As a retiree relying on dividends, a steady market is welcome news indeed. Hopefully, this momentum can be sustained through the next fiscal announcement.
D
David Thorne27 Oct
The inflation data is the real key here. If the Bank of England decides to keep rates higher for longer to combat sticky service inflation, I suspect we will see the FTSE pull back quite sharply.
S
Sarah Jenkins27 Oct
I am not so sure about this steady course narrative. With the cost of living still hitting families so hard, these market figures feel like they are completely disconnected from the reality on the high street.
A
Arthur Penhaligon27 Oct
It is good to see the FTSE holding its own despite the volatility we are seeing elsewhere. I remain cautiously optimistic that we might see some stability in interest rates by the end of the quarter.