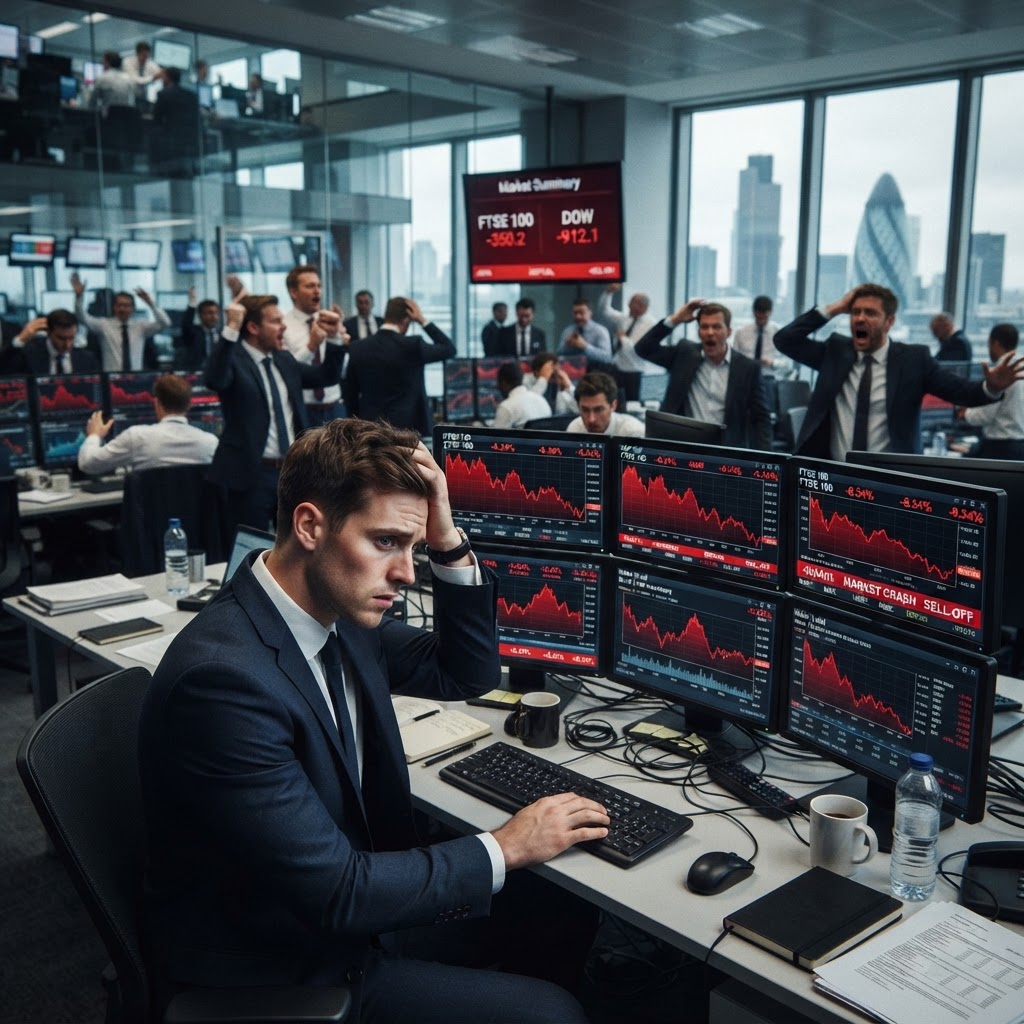
A Week of Retrenchment The City of London endured a bruising week of trading as the FTSE 100 index recorded its most significant percentage decline since April 2026. The blue-chip index, often viewed as a bellwether for the domestic economy, struggled to maintain its footing as a global rout in the bond markets sent tremors through equity valuations. By the close of play on Friday, the sentiment among institutional investors had shifted decisively from cautious optimism to defensive positioning.
At the heart of the volatility lies a dramatic repricing of sovereign debt. As long-term yields continue their upward trajectory, the traditional 'risk-free' rate has exerted downward pressure on stocks, particularly those in the growth and technology sectors which are disproportionately sensitive to discount rates. The surge in bond yields reflects a growing apprehension that central bank interest rates may remain elevated for longer than previously anticipated, challenging the consensus view that the economy would experience a smooth transition into the final months of the year.
Economic Clouds Gather Data released in the opening days of October has served to exacerbate the prevailing anxiety. Surveys of purchasing managers and business leaders suggest a perceptible decline in corporate confidence, as firms grapple with the dual challenges of cooling demand and input price inflation. The energy sector, in particular, remains a focal point for investors, with rising fuel costs threatening to erode profit margins across the manufacturing and logistics industries.
Economists have pointed to the 'October squeeze' as a potential drag on GDP growth for the remainder of the quarter. While household spending showed resilience through the summer, there is palpable concern that the cumulative impact of rising energy costs and tighter financial conditions is beginning to dampen consumer sentiment. The FTSE 100, which carries a heavy weighting toward commodity producers and banking institutions, has found little shelter from this macro-economic malaise.
The Debt Dilemma The turmoil within the gilt market is not merely a technical adjustment; it represents a fundamental recalibration of investor expectations regarding fiscal policy and the long-term cost of borrowing. Portfolio managers, having spent much of the year rotating into equities, are now reconsidering their allocations as fixed-income assets begin to offer yields that are increasingly competitive relative to dividend-paying stocks.
Market participants are now turning their attention to the upcoming budgetary announcements from the Treasury, seeking clarity on the government's fiscal trajectory. The current volatility serves as a reminder that equity markets are acutely susceptible to sudden changes in macroeconomic conditions. Until there is a cooling of bond market tensions, it is likely that the FTSE will continue to experience bouts of erratic trading.
“The surge in bond yields reflects a growing apprehension that central bank interest rates may remain elevated for longer than previously anticipated, challenging the consensus view that the economy would experience a smooth transition into the final months of the year.”