National Post UK
The Great Pivot: Monetary Policy Tightening Looms as Threadneedle Street Breaks Its Three-Year Stasis

As inflation continues to exert a persistent grip on the British economy, the Bank of England is widely expected to brea

The National Post

HomeFinance
Finance

The Great Pivot: Monetary Policy Tightening Looms as Threadneedle Street Breaks Its Three-Year Stasis

As inflation continues to exert a persistent grip on the British economy, the Bank of England is widely expected to break its long-standing period of monetary inertia. Today's anticipated quarter-point increase to 4% marks a pivotal shift in the nation's financial landscape.

CW

Charlotte Webb

Finance Correspondent

Published 5 November 2026·about 2 hours ago 3 min read
Text
Share

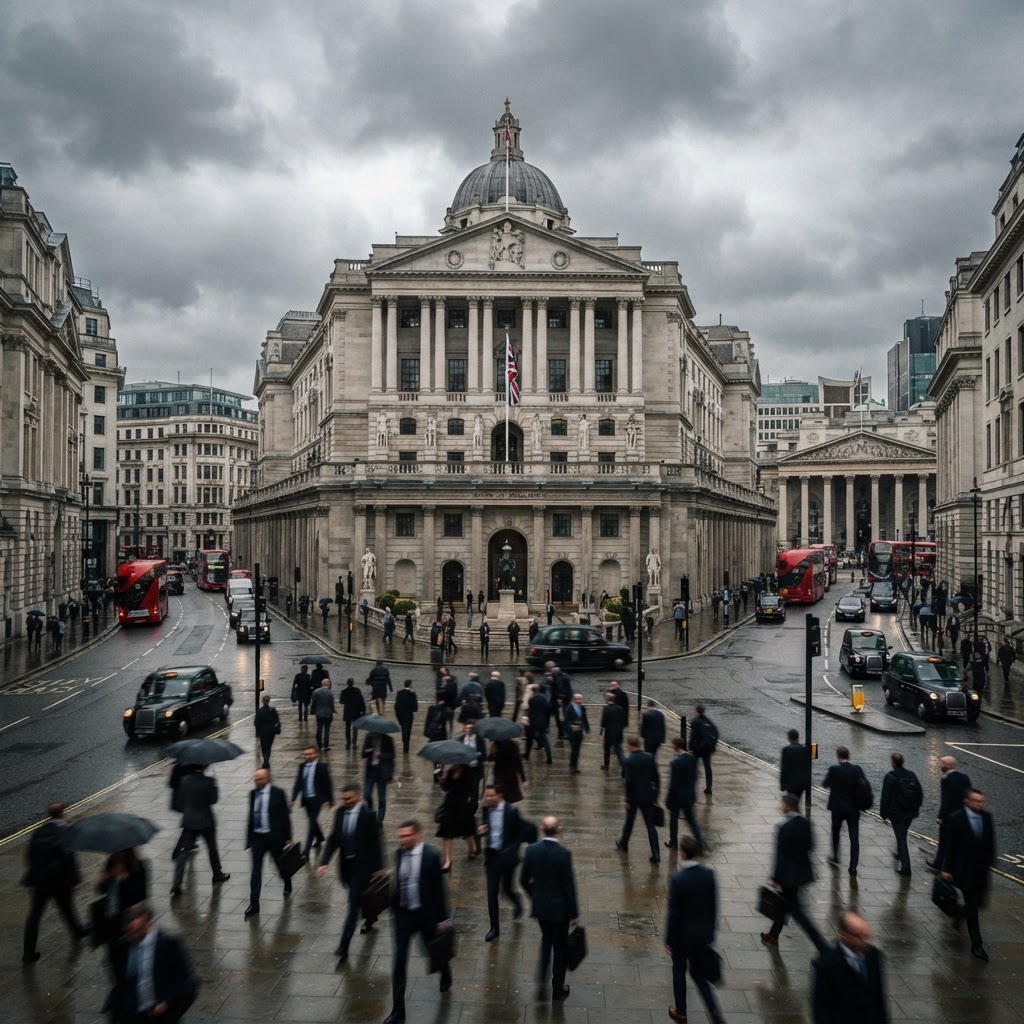
The End of an Era of Stability For more than three years, the Monetary Policy Committee (MPC) at the Bank of England has adhered to a strategy of steady-state interest rates, holding the base rate at 3.75% even as the global economy weathered profound shifts. Today, that period of profound stability appears to be drawing to a close. As the City of London awaits the 12:00 GMT announcement, the consensus among economists and financial institutions is that Governor Andrew Bailey and his colleagues will sanction an increase to 4%, marking the first upward movement in the cost of borrowing since 2023. The decision represents a calculated response to a cocktail of persistent inflationary pressures and the escalating volatility currently radiating from international markets.

The Inflationary Imperative The impetus for this policy pivot is clear to those watching the consumer price indices. Despite initial projections that inflation might prove transitory, the reality for British households has remained stubbornly high, with energy costs and supply chain bottlenecks compounding to erode purchasing power. Central bankers have reached a point where the risks of inaction—namely, the entrenchment of long-term inflationary expectations—outweigh the risks of cooling a fragile economic recovery. The move to 4% is designed to signal the Bank’s commitment to its primary mandate of price stability, an imperative that has become increasingly difficult to balance against the desire to stimulate growth.

Consumer Impact and the Mortgage Trap For the average British consumer, the transition to a higher-rate environment will be felt most acutely in the property market and retail credit sectors. With a significant proportion of the UK mortgage market transitioning away from ultra-low fixed-rate deals, a move to 4% will likely translate into higher monthly repayments for hundreds of thousands of homeowners. Financial advisors are already warning that the days of cheap debt are receding into the rearview mirror. Credit card providers and personal loan lenders are anticipated to follow the Bank’s lead swiftly, tightening access to capital and increasing the cost of borrowing for everyday purchases. This shift effectively marks the end of the post-pandemic stimulus era, forcing both households and corporations to recalibrate their financial planning for a more austere reality.

A Global Context The Bank of England does not act in a vacuum. Its decision today occurs against a backdrop of global monetary contraction. With the US Federal Reserve and the European Central Bank both signaling their intentions to recalibrate policy, the Bank of England is essentially attempting to maintain the attractiveness of Sterling while keeping the UK competitive in an era where global capital is becoming more expensive. Analysts note that today’s decision is unlikely to be an isolated event. Many in the investment community are looking beyond this afternoon’s headline, seeking guidance on the trajectory for 2027. If today’s move is merely the beginning of a tightening cycle, the economic cooling effect could be more pronounced than current forecasts suggest.

The Road Ahead As the MPC deliberates behind the hallowed doors of Threadneedle Street, the prevailing sentiment is one of cautious resolve. There is no simple path to tempering inflation without imposing a degree of pain upon the broader economy. The challenge for the Bank remains the delicate art of ‘calibrating the dial’—moving rates high enough to dampen demand, yet not so aggressively as to precipitate a significant contraction. As the afternoon unfolds, all eyes will be on the tone of the accompanying policy statement, which will provide the necessary narrative context for what is undeniably the most significant monetary policy shift in a generation.

TopicsBank of EnglandInterest RatesMonetary PolicyUK EconomyInflationFinanceMortgagesAndrew Bailey
Share

About the Author

CW

Charlotte Webb

Finance Correspondent

Charlotte Webb reports for National Post UK with a focus on rigorous analysis and authoritative journalism — a trusted voice across British public life.

Reader Discussion · 6

Subscribers can join the conversation.

SUBSCRIBE TO COMMENT →
L
Liam O'Connor5 Nov

As a small business owner, uncertainty is the biggest killer. I just hope the Bank provides clear guidance on the path forward so we can plan our investments for the next two years.

G
Geoffrey Miller5 Nov

I am skeptical that small incremental changes will do anything to dampen the volatility we are seeing in the global markets. It feels like a reactive gesture rather than a strategic pivot.

F
Fiona Campbell5 Nov

Finally some sensible movement from Threadneedle Street. Savers have been hammered for years, so it is high time we saw a shift in policy to reflect the current economic climate.

D
David Thorne5 Nov

Analytical perspective: the MPC is clearly reacting to the labour market tightness we have seen over the last quarter. Whether a rate hike will actually curb cost-push inflation remains to be seen.

S
Sarah Jenkins5 Nov

This is going to be incredibly tough for families already struggling with their mortgage renewals. I hope they haven't left it too late to balance the need for stability with the reality of household budgets.

A
Arthur Penhaligon5 Nov

It was only a matter of time before the Bank of England moved. Keeping rates at 3.75% for this long while inflation has been ticking up was arguably unsustainable for the currency.
More from Finance

Most Read in Finance

Morning Briefing

The day's top stories, before 7am

Join 40,000 readers who start their morning with National Post UK.