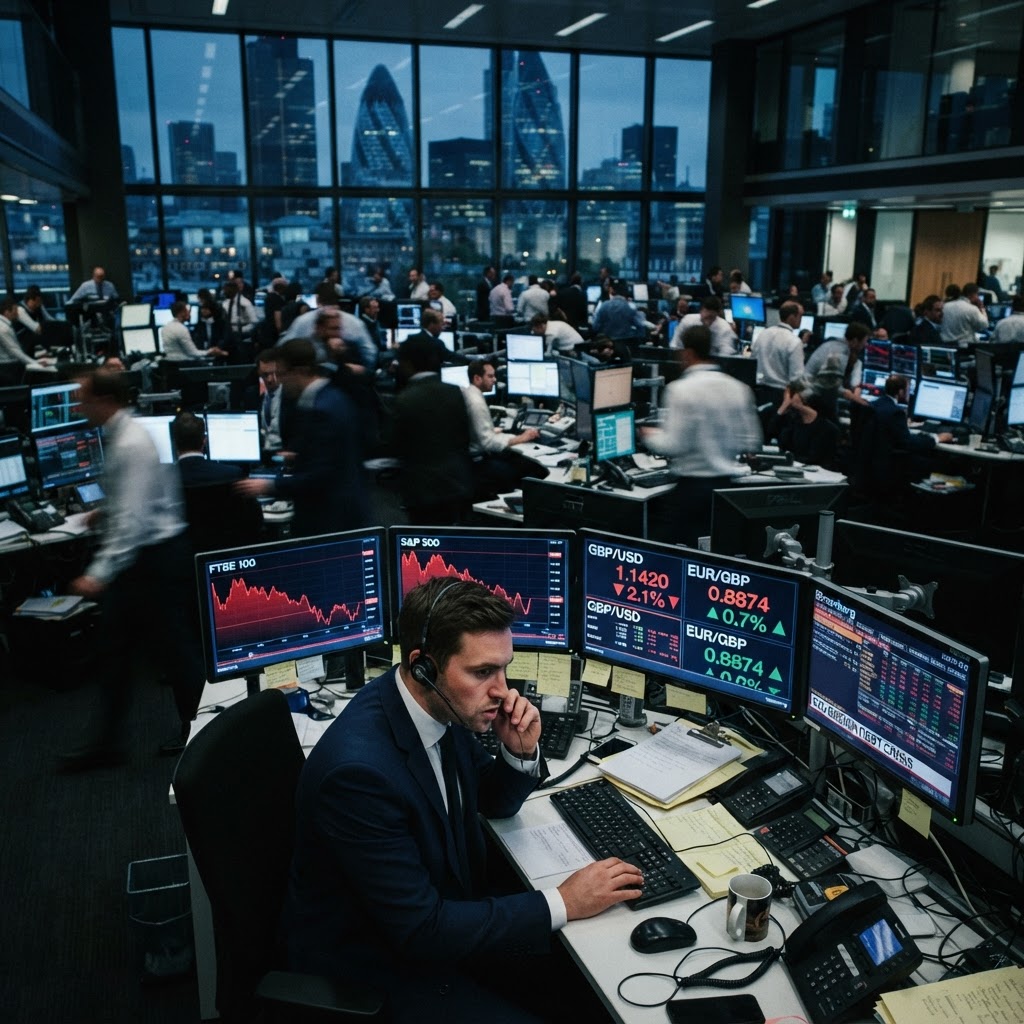
Sterling Under Siege: Sovereign Debt Worries Trigger Record Short Positions
Market confidence in the UK fiscal trajectory has faltered as borrowing requirements outpace official forecasts. With bond yields touching levels not seen in two decades, the City braces for a prolonged period of monetary tightening.
CW
Charlotte Webb
Finance Correspondent
Published 28 September 2026·4 days ago 3 min read
Text
TopicsBritish PoundFTSE 100Bank of EnglandUK EconomySovereign DebtFinancial Markets
About the Author
CW
Charlotte Webb
Finance Correspondent
Charlotte Webb reports for National Post UK with a focus on rigorous analysis and authoritative journalism — a trusted voice across British public life.
Reader Discussion · 5
Subscribers can join the conversation.
SUBSCRIBE TO COMMENT →J
James Sinclair28 Sept
I have moved a portion of my savings into foreign assets to hedge against this. It is a sad state of affairs when you feel you have to protect yourself against your own national currency.
E
Eleanor Rigby28 Sept
The instability in the bond market is the real story here, not just the currency volatility. Until the government signals a genuine commitment to fiscal discipline, I cannot see why international investors would stick around.
D
David Thorne28 Sept
Let us not panic just yet. Shorting the pound has been a favourite pastime for hedge funds for years, and they often get it wrong when they underestimate the resilience of our financial institutions.
S
Sarah Jenkins28 Sept
I am not an economist, but I am certainly feeling the squeeze at the petrol pump and the supermarket. It feels like the pound is becoming a secondary concern compared to the actual cost of living crisis on the ground.
A
Arthur Penhaligon28 Sept
It seems the markets are finally reacting to the lack of a coherent long-term fiscal strategy. We have been kicking the can down the road for too long and the chickens are coming home to roost.