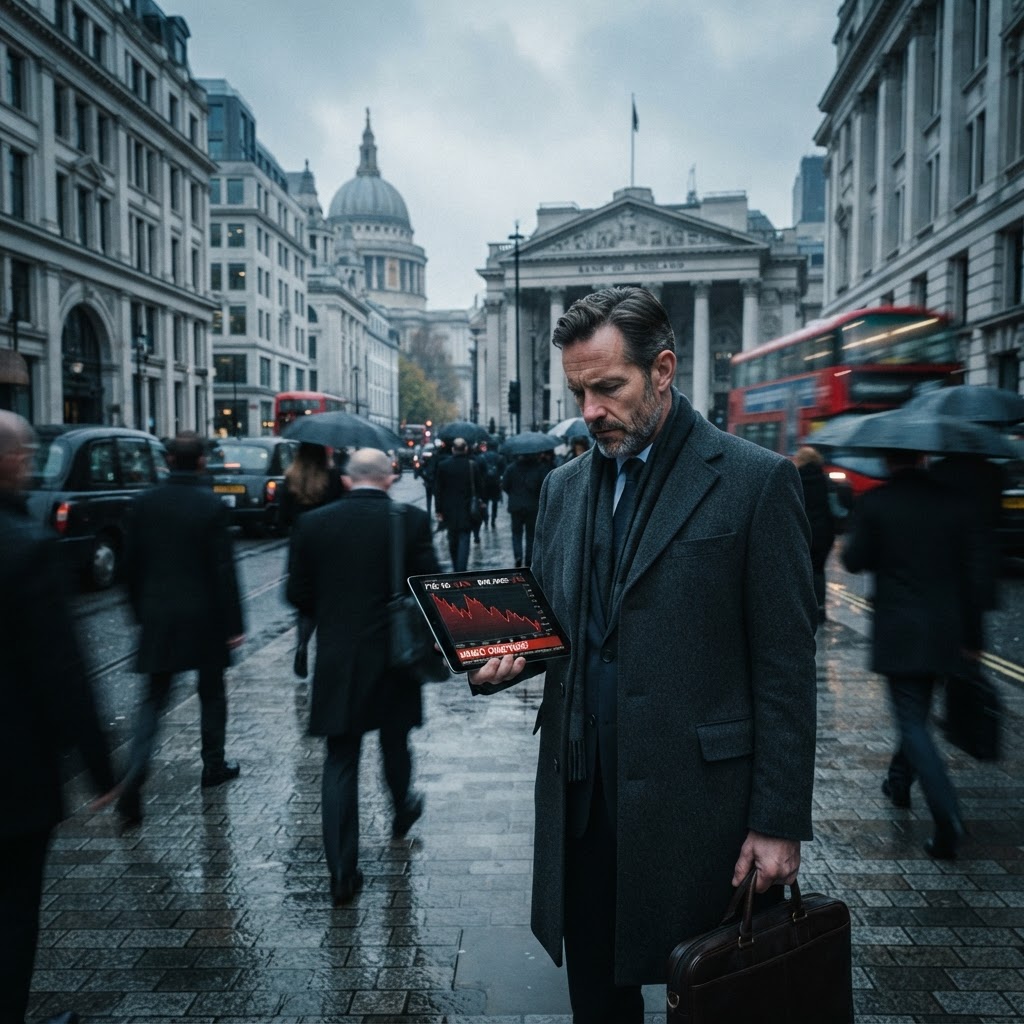
Market Fragility Returns: The FTSE 100 Stumbles as Autumn Economic Chill Sets In
As the final quarter of 2026 commences, British financial markets are grappling with a toxic combination of cooling business sentiment and persistent inflationary pressures. Investors remain cautious as the reality of a constrained economic environment takes hold across the City.
MS
Marcus Stone
Finance Correspondent
Published 6 October 2026·7 days ago 3 min read
Text
TopicsUK EconomyFTSE 100Bank of EnglandMarket AnalysisBusiness News
About the Author
MS
Marcus Stone
Finance Correspondent
Marcus Stone reports for National Post UK with a focus on rigorous analysis and authoritative journalism — a trusted voice across British public life.
Reader Discussion · 4
Subscribers can join the conversation.
SUBSCRIBE TO COMMENT →E
Elena Richards6 Oct
I am curious to see if the central bank intervenes before the end of the month. The current climate makes it very difficult for those of us trying to plan for long-term growth in our portfolios.
D
David Thorne6 Oct
This is exactly what happens when business confidence hits rock bottom due to lack of clear direction from Westminster. Small businesses are being squeezed from every angle and the FTSE is just reflecting that misery.
S
Sarah Jenkins6 Oct
While the headline makes it sound dramatic, this is just a standard market correction after a strong summer period. Investors shouldn't be panicking over a few days of red ink on the screens.
A
Arthur Penhaligon6 Oct
It feels like we have been expecting this autumn downturn for months given the persistent inflation figures. I have moved most of my pension pot into gilts until the volatility settles down.