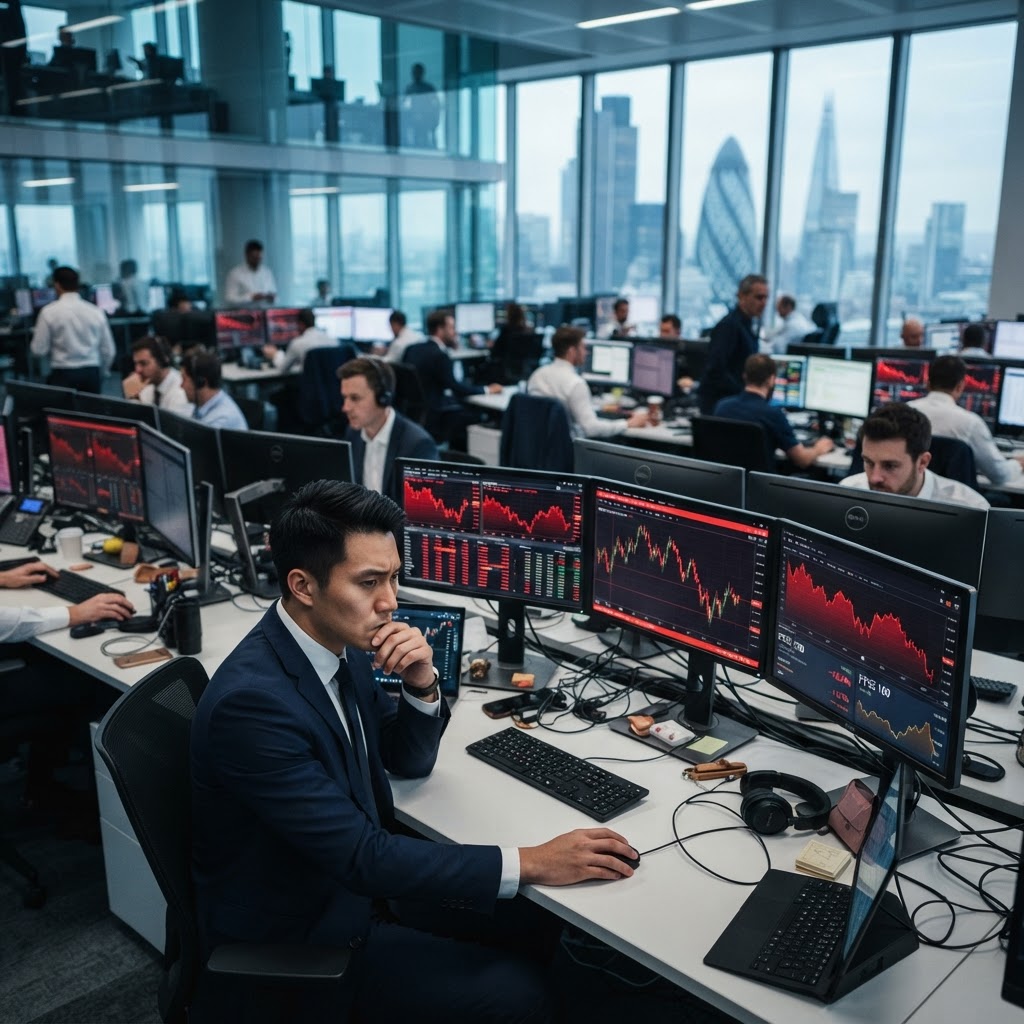
London’s blue-chip index has snapped a three-day rally as cooling sentiment in the banking sector coincides with a sharp uptick in gilt yields. Market participants are increasingly wary of policy shifts ahead of the Chancellor’s late October fiscal statement.
A Shift in Market Sentiment
The relentless optimism that defined the early part of the week on the London Stock Exchange ground to a halt on Wednesday. After recording three consecutive days of gains that pushed the FTSE 100 toward recent highs, the index succumbed to gravity, closing lower as the realities of a tightening macroeconomic environment began to weigh on investor confidence. The retreat was broad-based, but the damage was most acute among the heavyweights of the financial sector, which have struggled to maintain momentum in the face of shifting monetary policy expectations.
The Weight of Rising Yields
At the heart of the afternoon’s malaise were surging bond yields. The yield on the ten-year gilt, the benchmark for UK government borrowing, saw a sharp climb as traders repriced their expectations for long-term interest rates. For the banking sector, while higher rates can theoretically improve net interest margins, the current move is interpreted by many as a signal of stickier inflation and potential economic cooling, which threatens loan demand and increases the risk of credit impairments. As yields march upward, the relative appeal of equities begins to diminish, prompting institutional investors to pivot toward the perceived safety of fixed-income instruments.
Energy Costs and Global Headwinds
Compounding the pressure on the FTSE 100 was the volatile state of global energy markets. A persistent rise in crude oil prices has reignited concerns regarding the 'higher for longer' narrative on global inflation. For a market like the FTSE 100, which hosts several energy majors, one might expect oil strength to provide a hedge. However, the broader economic impact of expensive energy is acting as a drag on consumer-facing stocks and industrial firms, which fear that elevated costs will continue to erode margins that are already under scrutiny.
The Shadow of the Healey Budget
The atmosphere in the City is increasingly defined by the impending budget address from Chancellor John Healey, scheduled for 28 October. Uncertainty is a volatile agent in capital markets, and the lack of clarity regarding the government’s fiscal trajectory is forcing a tactical withdrawal among many asset managers. There is growing concern that the Chancellor may seek to increase the corporate tax burden or implement changes to capital gains tax, measures that could fundamentally alter the attractiveness of UK-listed assets. Analysts are warning that until the government provides a coherent roadmap for fiscal sustainability, volatility is likely to remain the defining characteristic of the coming fortnight.
Looking Ahead
As the market digests these developments, the consensus among analysts is that the next few weeks will be defined by a delicate balancing act. Investors are waiting to see if the government can balance the need for public spending with the constraints imposed by the bond markets. For now, the FTSE 100 remains in a state of flux, suspended between a resilient domestic economy and the harsh, tightening conditions of the international debt landscape. Investors would do well to prepare for continued turbulence as the October deadline approaches.