A Resilient Start to the Quarter The United Kingdom economy demonstrated surprising vigour in July, delivering a 0.4 per cent expansion in gross domestic product that has recalibrated growth forecasts for the remainder of the year. Following a period of stagnation that had left policymakers and the City of London bracing for a more tepid autumn, the data suggests that the nation’s pivot toward high-growth digital sectors is finally manifesting in tangible economic output.
This growth figure, which outperformed the modest 0.1 per cent expansion projected by most independent economists, provides a necessary buffer against the prevailing headwinds of elevated energy prices and the persistent spectre of core inflation. While the broader economic landscape remains complex, the resilience exhibited by the services sector, particularly in the realm of computing and technical consultancy, indicates that the UK is successfully capturing value from the global artificial intelligence boom.
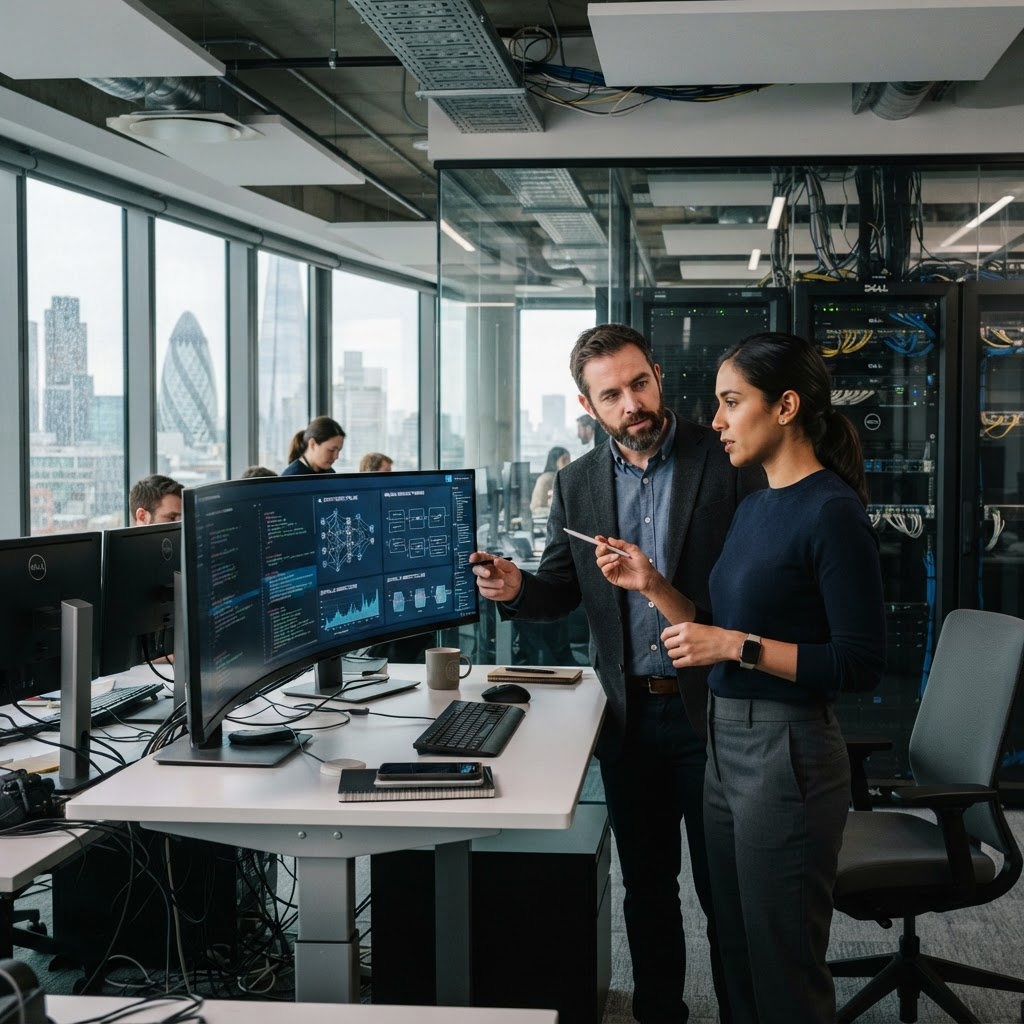
The AI Catalyst At the heart of the July surge is an aggressive acceleration in tech sector activity. Data from the Office for National Statistics reveals that professional and technical services saw a substantial uptick, reflecting the increased capital expenditure directed toward large-scale AI integration across domestic firms. Businesses, once hesitant to commit to digitisation during the high-interest-rate environment of the past eighteen months, have shifted their strategy, viewing AI adoption as a primary vehicle for productivity gains.
This shift is not merely speculative. It represents a fundamental restructuring of British corporate workflows. Large-scale infrastructure projects, ranging from data centre construction to the refinement of proprietary machine-learning models, have acted as a multiplier for GDP. The technology sector, once considered a niche driver of the wider economy, now commands a central role in sustaining growth momentum.
Persistent Risks on the Horizon Despite the upbeat figures, analysts remain cautious regarding the durability of this expansion. The energy sector continues to pose a significant risk to the headline figures. With Brent crude prices hovering at levels that threaten to squeeze profit margins across the manufacturing and logistics industries, the threat of 'stagflationary' pressure has not been entirely eradicated. The Bank of England’s Monetary Policy Committee remains vigilant, cognisant that domestic price pressures could be reignited should the energy market experience further volatility.
Furthermore, while July provided a strong start, the performance of the consumer discretionary sector remains muted. Retail spending has struggled to keep pace with the corporate sector’s digitisation efforts, suggesting a K-shaped recovery where the high-skill economy thrives while the high-street struggles under the weight of sustained cost-of-living concerns.
“The surge in artificial intelligence activity suggests that the United Kingdom is successfully transitioning into a high-tech engine of growth, effectively decoupling parts of the economy from traditional, slower-growth sectors.”
Looking Toward the Autumn Statement The unexpected growth will inevitably influence the political and fiscal discourse as the government prepares for the upcoming Autumn Statement. Should the momentum persist through August and September, the Treasury may find itself with a slightly larger fiscal headroom than previously estimated. However, officials are expected to remain reticent, prioritising debt consolidation and inflation control over immediate stimulus.
In conclusion, the July GDP figures offer a welcome reprieve for an economy that has spent much of the year in the doldrums. Whether this performance constitutes a structural shift or a transient burst of activity remains to be seen. What is clear, however, is that the strategic investment in artificial intelligence has provided a critical engine for growth, potentially shielding the UK from the sharper edges of a global economic slowdown.