A Winter of Discontent The latest data from the Office for National Statistics has confirmed that the UK is facing a renewed inflationary impulse, with the Consumer Prices Index (CPI) rising to 3.6 per cent in October. This unexpected jump to a one-year high shatters the cautious optimism that had begun to permeate the Square Mile, signalling that the path to the Bank of England’s two per cent target remains fraught with volatility. The return of persistent price growth has once again placed the burden of economic stability squarely on the shoulders of Threadneedle Street.
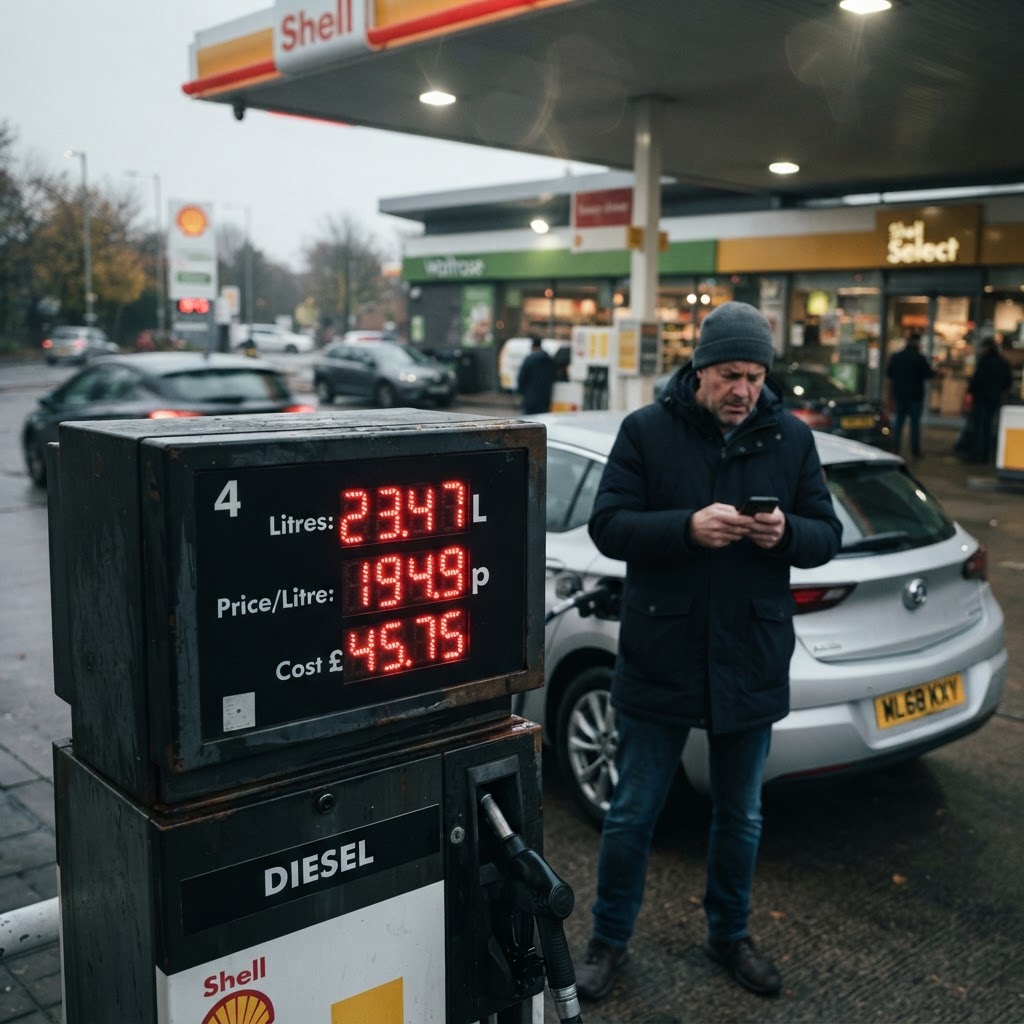
The Diesel Dilemma At the heart of the resurgence in prices is the energy sector, specifically the unprecedented cost of diesel. While global crude benchmarks have fluctuated throughout the autumn, the structural challenges in fuel refining and distribution have pushed domestic pump prices to record levels. For a logistics-reliant economy, this shift serves as a potent inflationary multiplier, as increased transport costs are inevitably passed down to the consumer at the supermarket checkout and in the price of essential manufactured goods.
Monetary Policy at a Crossroads The Bank of England’s Monetary Policy Committee, currently presiding over a Bank Rate of 4 per cent, finds itself in a precarious position. The central bank has long maintained that it would act decisively to anchor inflation expectations, yet the cooling of broader industrial output complicates the appetite for further tightening. As the 17 December policy meeting approaches, the divide between those advocating for a pause to protect growth and those prioritising the erasure of entrenched inflation is expected to widen significantly.
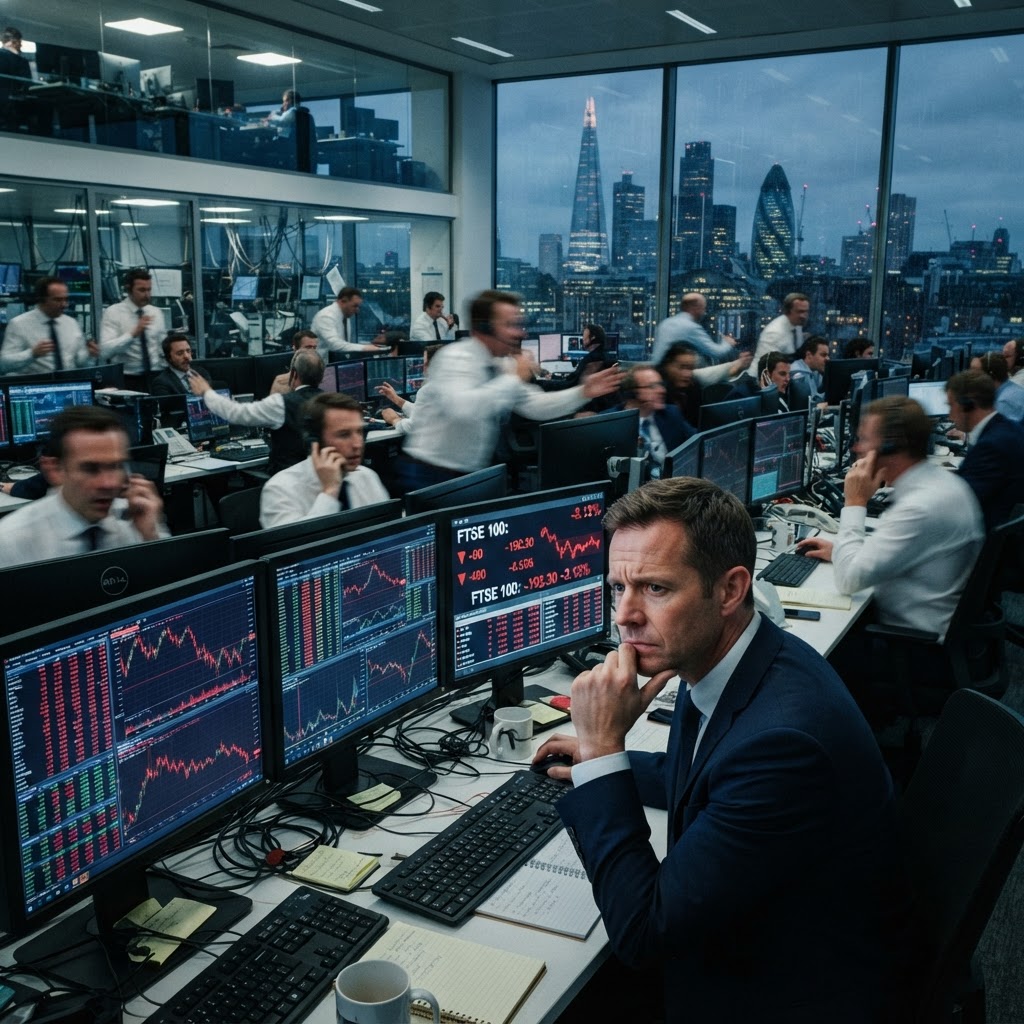
Market Reactions and Economic Sentiment Financial markets reacted swiftly to the news, with the FTSE 100 retreating in early trading and the pound sterling losing ground against the dollar and the euro. Investors are now recalibrating their expectations for the interest rate trajectory, with many analysts suggesting that a hike is not merely a possibility but a probability. The concern among institutional investors is that prolonged inflation at these levels will erode the real-terms purchasing power of the British consumer, potentially leading to a stagnation in service sector activity through the early months of 2027.
Expert Perspectives Economic observers have cautioned against reading too much into a single month’s data, though many acknowledge that the trend has shifted. Dr Elena Thorne, a lead economist at the Institute for Fiscal Studies, noted that the core inflation numbers remain stubbornly high, suggesting that the inflationary impulse is beginning to bleed beyond energy and into the services sector. Whilst the government maintains that the pressures are largely imported, the internal cost base of the UK economy is showing signs of hardening, making the Bank of England’s task substantially more difficult than it appeared just three months ago.
As the winter period sets in, the dual challenge of high fuel costs and a looming policy tightening cycle presents a significant test for the Chancellor and the Governor alike. With wage growth failing to keep pace with the rising cost of essentials, the social implications of this inflationary cycle are becoming a focal point of parliamentary debate. The coming weeks of December will likely prove pivotal in determining whether the economy can stabilise or if the Bank will be forced into a more aggressive stance to restore price equilibrium.