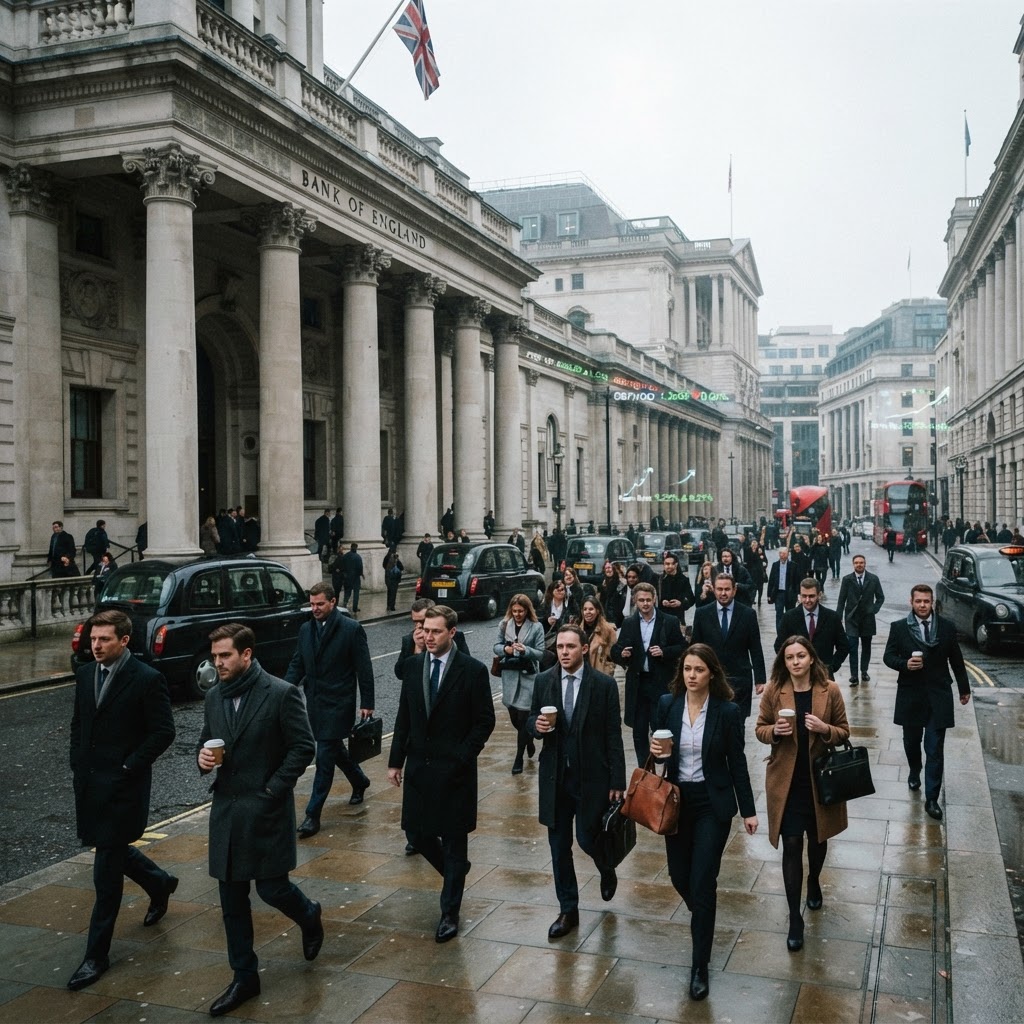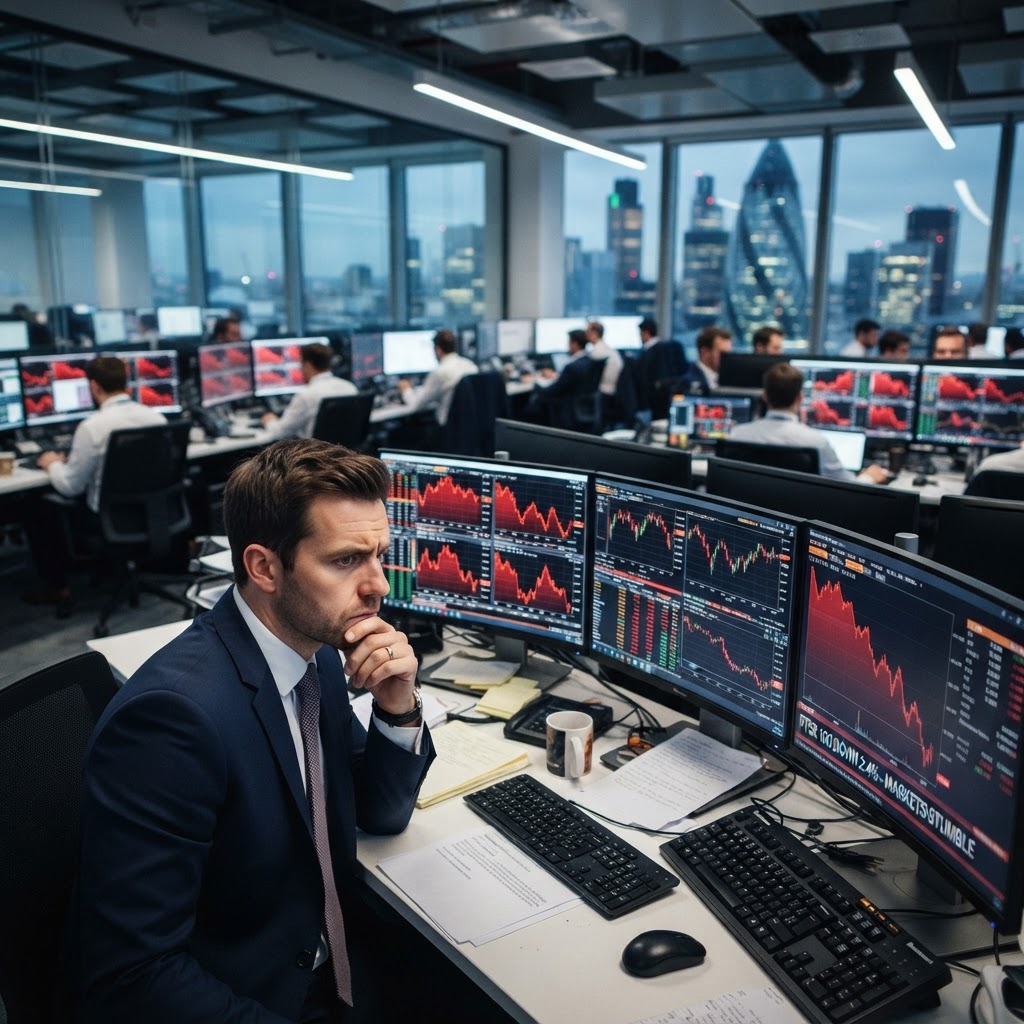
Fiscal recalibration in the City The City of London has spent the latter half of the week parsing the long-term implications of the Autumn Budget delivered by Chancellor John Healey. By the close of trading on October 30, 2026, the FTSE 100 recorded a modest gain of 0.07%, finishing at 10,729.78. While the uptick was marginal, the underlying sentiment suggests a market that is relieved to have avoided more radical fiscal intervention, despite the imposition of specific tax levies on banking institutions and the gambling sector.
These targeted measures, intended to bolster the exchequer, were largely anticipated by market participants. Nevertheless, the reaction from banking stocks remained lukewarm, as analysts recalibrated their earnings projections to account for the increased tax burden. The gambling sector, meanwhile, faced renewed scrutiny, though diversified portfolios helped dampen the impact on the wider index.
The international monetary backdrop Beyond the domestic fiscal theatre, the attention of traders has been drawn across the Atlantic. The United States Federal Reserve’s decision to maintain interest rates at 4.00% provided a stable backdrop for global capital markets. The Fed’s reluctance to pivot aggressively has served as a tempering force, preventing the sudden bouts of volatility that have characterized the latter half of the year. This stability in American monetary policy has provided the Bank of England with a necessary, if fleeting, window of calm to assess domestic inflationary pressures.
Sterling has demonstrated remarkable resilience, maintaining a steady footing against both the dollar and the euro. Currency analysts attribute this stability to a growing perception that the UK government’s fiscal stance, while restrictive, is disciplined. The avoidance of populist spending sprees has gone some way toward reassuring the international investor community, which remains hypersensitive to the UK’s gilt market stability.
Looking toward Threadneedle Street The immediate concern for institutional investors remains the trajectory of the Bank of England. As gilt yields continue to fluctuate, the market is bracing for the next Monetary Policy Committee (MPC) meeting. There is a palpable tension between the necessity of curbing inflation and the risk of stunting the nascent economic growth signalled in the latest Treasury forecasts.
Dr. Eleanor Vance, a senior economist at a leading City brokerage, suggests that the market is in a wait-and-see posture. The Chancellor has done enough to signal a commitment to stability, but the structural challenges of the UK economy remain. Inflationary persistence, particularly in the services sector, means the Bank of England is unlikely to be lured into a premature easing cycle. Investors are currently pricing in a long plateau, rather than a rapid descent, in interest rates.
“The avoidance of populist spending sprees has gone some way toward reassuring the international investor community, which remains hypersensitive to the UK’s gilt market stability.”
Sectoral divergence While the broader index remained static, beneath the surface, there was evidence of rotation. Defensive stocks, such as utilities and consumer staples, attracted inflows as risk appetite waned. Conversely, the extractive industries saw slight declines, pressured by global commodity price shifts and a fluctuating demand forecast from emerging markets. This defensive positioning is common when fiscal landscapes shift, as fund managers prioritize capital preservation over speculative growth.
As we move into November, the focus will likely shift from the budget itself to the granular data on wage growth and consumer spending. Should these metrics suggest that the tax burden is beginning to dampen household consumption more rapidly than anticipated, we may see the Bank of England adopt a more dovish tone by year-end. Until then, the FTSE 100 serves as a mirror to the current UK malaise: not quite retreating, yet struggling to find the momentum required for a breakout.