Market Sentiment Sours as Inflationary Pressures and Geopolitical Risk Cloud the City
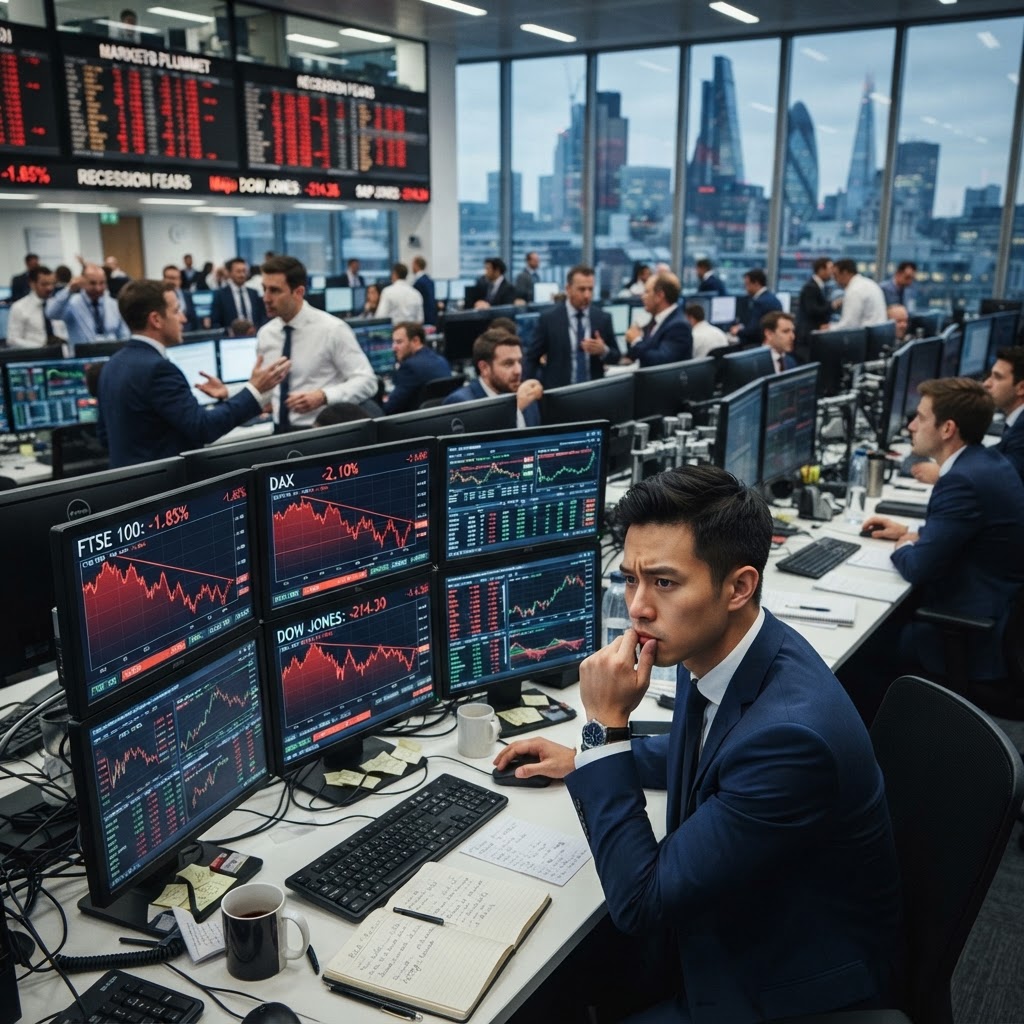
The FTSE 100 suffered its sharpest retreat in weeks as CPI data exceeded forecasts, leaving investors to recalibrate expectations for a Bank of England rate hike. Rising crude prices and wider European instability added to the bearish mood gripping the London Stock Exchange.
MS
Marcus Stone
Finance Correspondent
Published 24 October 2026·about 2 hours ago 3 min read
Text
TopicsFTSE 100Bank of EnglandInflationMarketsUK EconomyGeopolitics
About the Author
MS
Marcus Stone
Finance Correspondent
Marcus Stone reports for National Post UK with a focus on rigorous analysis and authoritative journalism — a trusted voice across British public life.
Reader Discussion · 5
Subscribers can join the conversation.
SUBSCRIBE TO COMMENT →J
James Sterling24 Oct
Investors are right to be cautious. When inflationary pressures start eating into corporate margins like this, growth forecasts usually get revised downwards pretty quickly.
M
Margaret Holloway24 Oct
Geopolitical uncertainty is the real culprit here. Until we have some clarity on the international front, I suspect we will see a lot more of this yo-yoing in the coming weeks.
D
David Thorne24 Oct
A 0.79 per cent drop is hardly a crash, is it? People love to panic over a minor correction when the index has been on a decent run for the past two weeks.
S
Sarah Jenkins24 Oct
I am not surprised at all. My pension fund has been volatile for months and this just confirms that the cost of living crisis is finally forcing the City to face reality.
A
Arthur Penhaligon24 Oct
It was only a matter of time before the market took a breather. These constant spikes were looking unsustainable given the state of the high street and the ongoing supply chain issues.