The FTSE 100 stumbled on Thursday as disappointing banking results and stubborn inflation figures rattled investor confidence. With the government’s maiden budget approaching, the City remains fixated on the delicate balance between public borrowing and interest rate trajectory.
A Challenging Landscape for Blue Chips
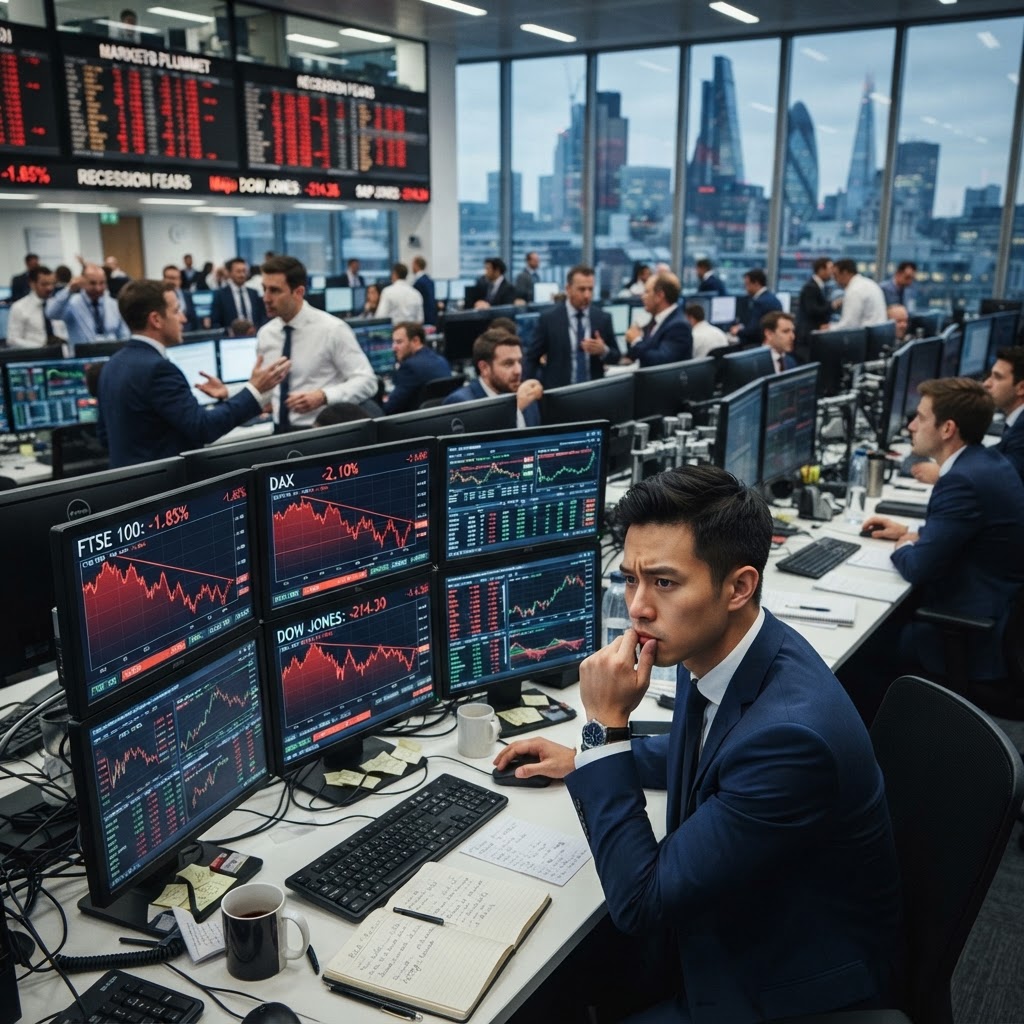
The London stock market faced a rigorous test of resilience on Thursday, as the FTSE 100 index shed more than 0.5 per cent of its value in a session defined by macroeconomic anxiety and corporate underperformance. Investors, already nursing concerns regarding the stability of public finances, were met with a double blow of higher-than-expected inflation data and a significant miss in quarterly earnings from one of the banking sector’s titans.
Barclays Under Pressure
Barclays proved to be the primary drag on the index, with shares tumbling more than 2 per cent after the lender unveiled third-quarter results that fell short of the Square Mile’s expectations. The firm reported investment banking revenue of £3.13 billion, a figure that failed to convince analysts that the division was capitalising on recent market volatility effectively. For a bank that has spent considerable effort pivoting towards a more streamlined, advisory-focused model, the shortfall invites renewed questions regarding the sustainability of current fee-generation strategies within its global markets business.
Inflation’s Stubborn Persistence
Compounding the gloom, the latest data from the Office for National Statistics confirmed that UK inflation climbed to 3.5 per cent in September. This uptick, which surpassed the consensus forecasts of City economists, complicates the task ahead for the Bank of England’s Monetary Policy Committee. With prices proving more durable than previously anticipated, the prospect of a swift return to the central bank’s two per cent target now appears increasingly remote. The data has acted as a catalyst for a repricing of interest rate expectations, with markets currently pricing in at least three quarter-point rate hikes between now and April 2027. Some analysts are already positioning for a potential increase as early as the November meeting, a move that would represent a significant pivot in the current policy cycle.
The Shadow of the Autumn Budget
Beyond the immediate market data, the overarching sentiment is one of extreme caution ahead of the upcoming UK budget. Recent figures indicating that public borrowing hit £24.5 billion for the month have only served to exacerbate investor anxiety. The Chancellor faces a gargantuan challenge: balancing the need for infrastructure investment and public service support against the constraints imposed by a high-debt environment. For institutional investors, the primary concern remains how much of the fiscal burden will be shifted onto corporate tax receipts. Any significant shift in fiscal policy is expected to generate volatility, particularly among the FTSE’s domestically focused mid-cap stocks, which have remained vulnerable to shifts in domestic consumption patterns. As the government prepares to unveil its fiscal strategy, the City is braced for a period of adjustment. The current climate is one of wait-and-see, where the absence of clear forward guidance from Whitehall is creating a vacuum that is currently being filled by bearish sentiment and a flight to liquidity.