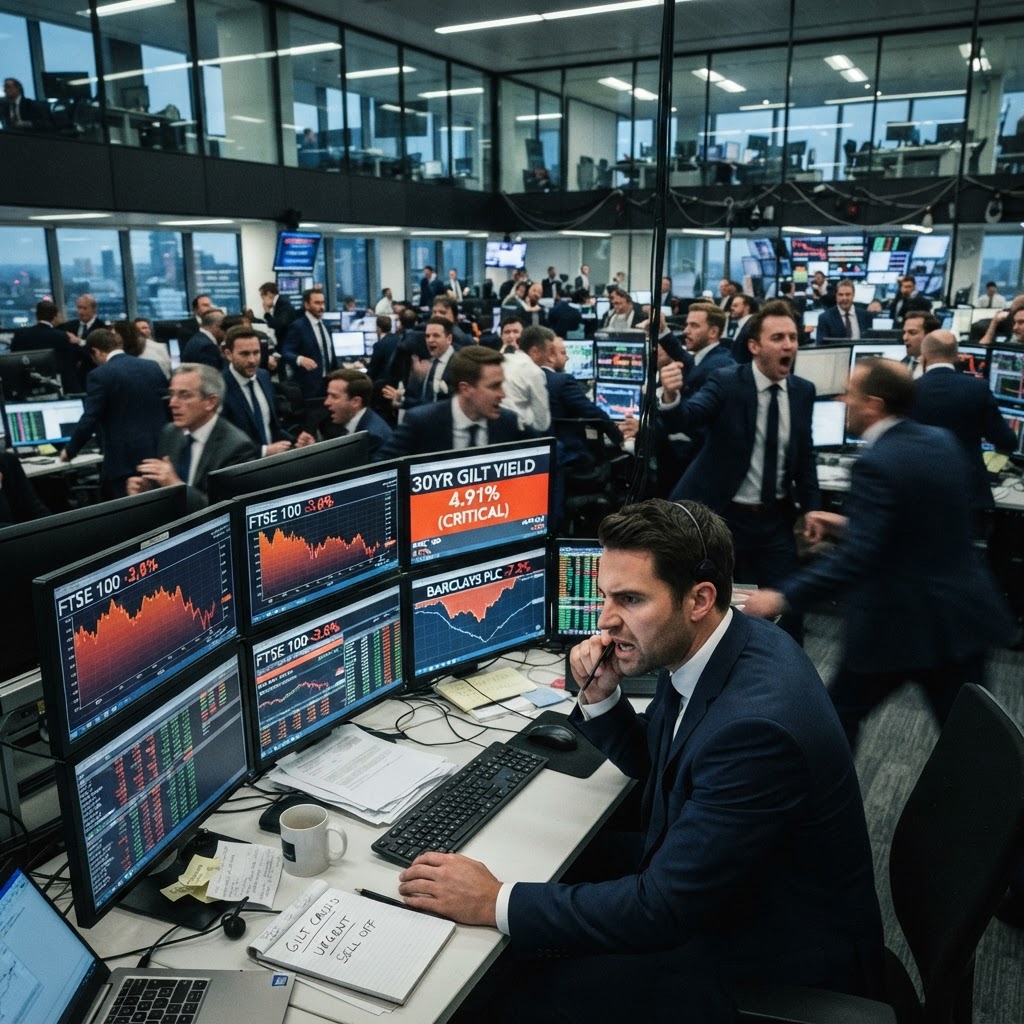
A Watershed Moment for the City The machinery of the British financial markets is currently weathering its most severe test in nearly two decades. As of the trading sessions concluding this week, the 30-year UK gilt yield breached the 6% threshold, a sobering milestone that marks its highest valuation since 1998. Simultaneously, the benchmark 10-year gilt has climbed to levels not witnessed since 2007, signalling an aggressive repricing of sovereign risk that has rippled across every asset class in the City of London.
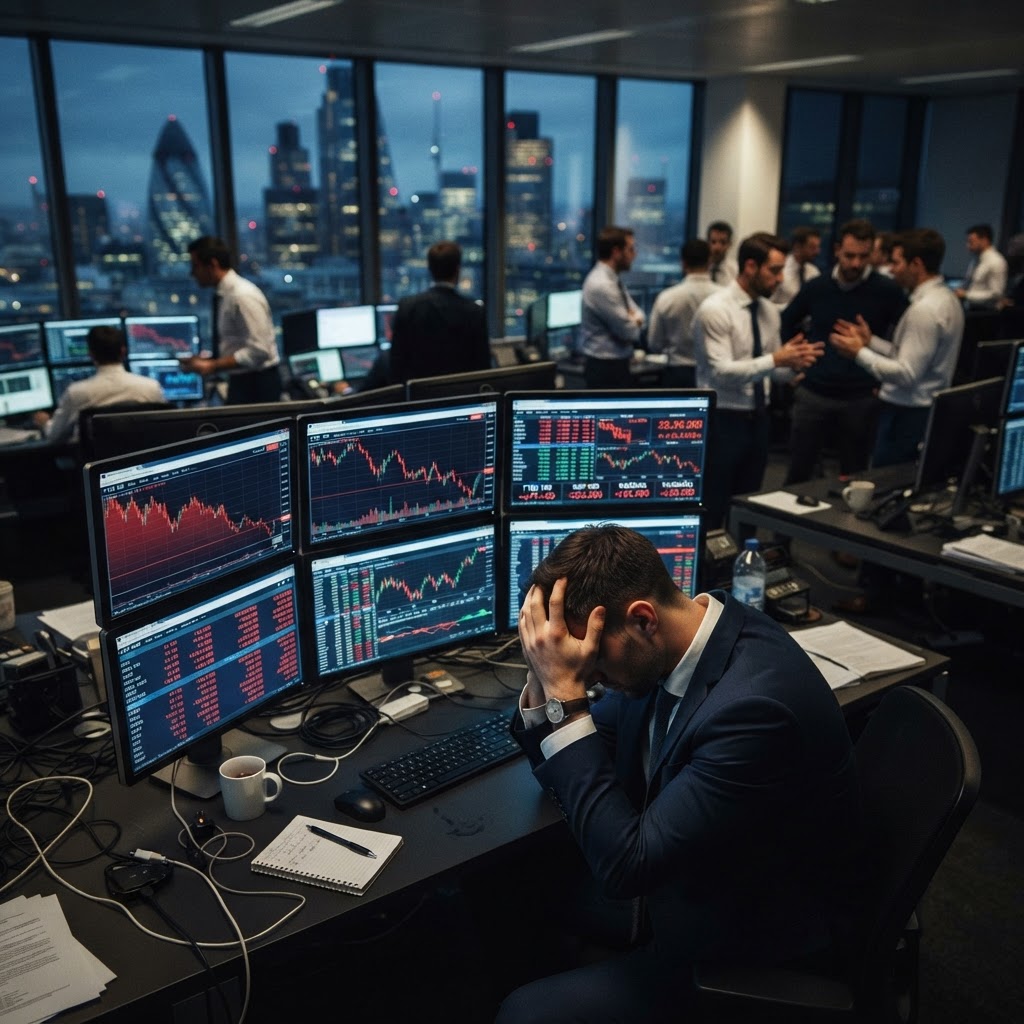
This surge in yields serves as a stark rebuke of current fiscal expectations, manifesting in a sharp correction for the FTSE 100, which has retreated to a three-month low. Banking stalwarts, including HSBC, Barclays, and NatWest, have borne the brunt of the sell-off as traders price in the dual threat of dampened economic growth and the necessity for higher capital reserves. The atmosphere on the trading floors is one of cautious containment as institutional investors attempt to decipher the signals emanating from Whitehall.
The Shadow of the Autumn Budget Central to this unrest is the impending Autumn Budget, a focal point of anxiety for both investors and industry leaders. The Institute of Directors’ latest index, which plummeted to -54 in September, offers a chilling snapshot of the prevailing sentiment among business leaders. The consensus among the corporate rank and file reflects a profound malaise, driven by the prospect of increased tax burdens and the persistent instability of energy costs. Such policy uncertainty acts as an anchor on investment, discouraging long-term capital allocation at a time when the British economy requires a clear trajectory.
The macroeconomic environment is further complicated by geopolitical instability in the Middle East, which continues to provide a floor for global energy prices. For the Bank of England, the challenge remains acute. Derivatives markets are now pricing in an 85–86% probability that the Monetary Policy Committee will resume interest rate hikes during its November meeting. Such a move, intended to extinguish the embers of inflation, threatens to further compress an economy already struggling with the weight of its own debt obligations.
The Domestic Fallout Beyond the sterile statistics of bond markets and indices, the impact is being felt acutely in the domestic sphere. The disappearance of sub-5% fixed-rate mortgage deals has effectively redefined affordability for a generation of homeowners and prospective buyers. The rapid escalation of borrowing costs is forcing a painful adjustment in household budgets, reducing discretionary spending and placing a ceiling on the recovery of the property sector. Economists suggest that we are entering a period where the ‘cost of living’ crisis is being augmented by a ‘cost of borrowing’ crisis, creating a pincer movement on consumer resilience.
As the United Kingdom enters the final quarter of 2026, the fragility of the recovery remains the defining narrative. While the government remains committed to its fiscal mandate, the market is demanding greater clarity. The coming weeks will be a definitive test of whether the administration can balance the necessity of fiscal rectitude with the urgent requirement to restore investor confidence and provide a pathway for sustainable growth.
“The surge in yields serves as a stark rebuke of current fiscal expectations, signalling an aggressive repricing of sovereign risk that has rippled across every asset class in the City of London.”